Prediction markets promise better forecasts. They may also turn democracy into another round-the-clock gambling product.
Who will be the next mayor of London, Ontario? There is now a market for that.
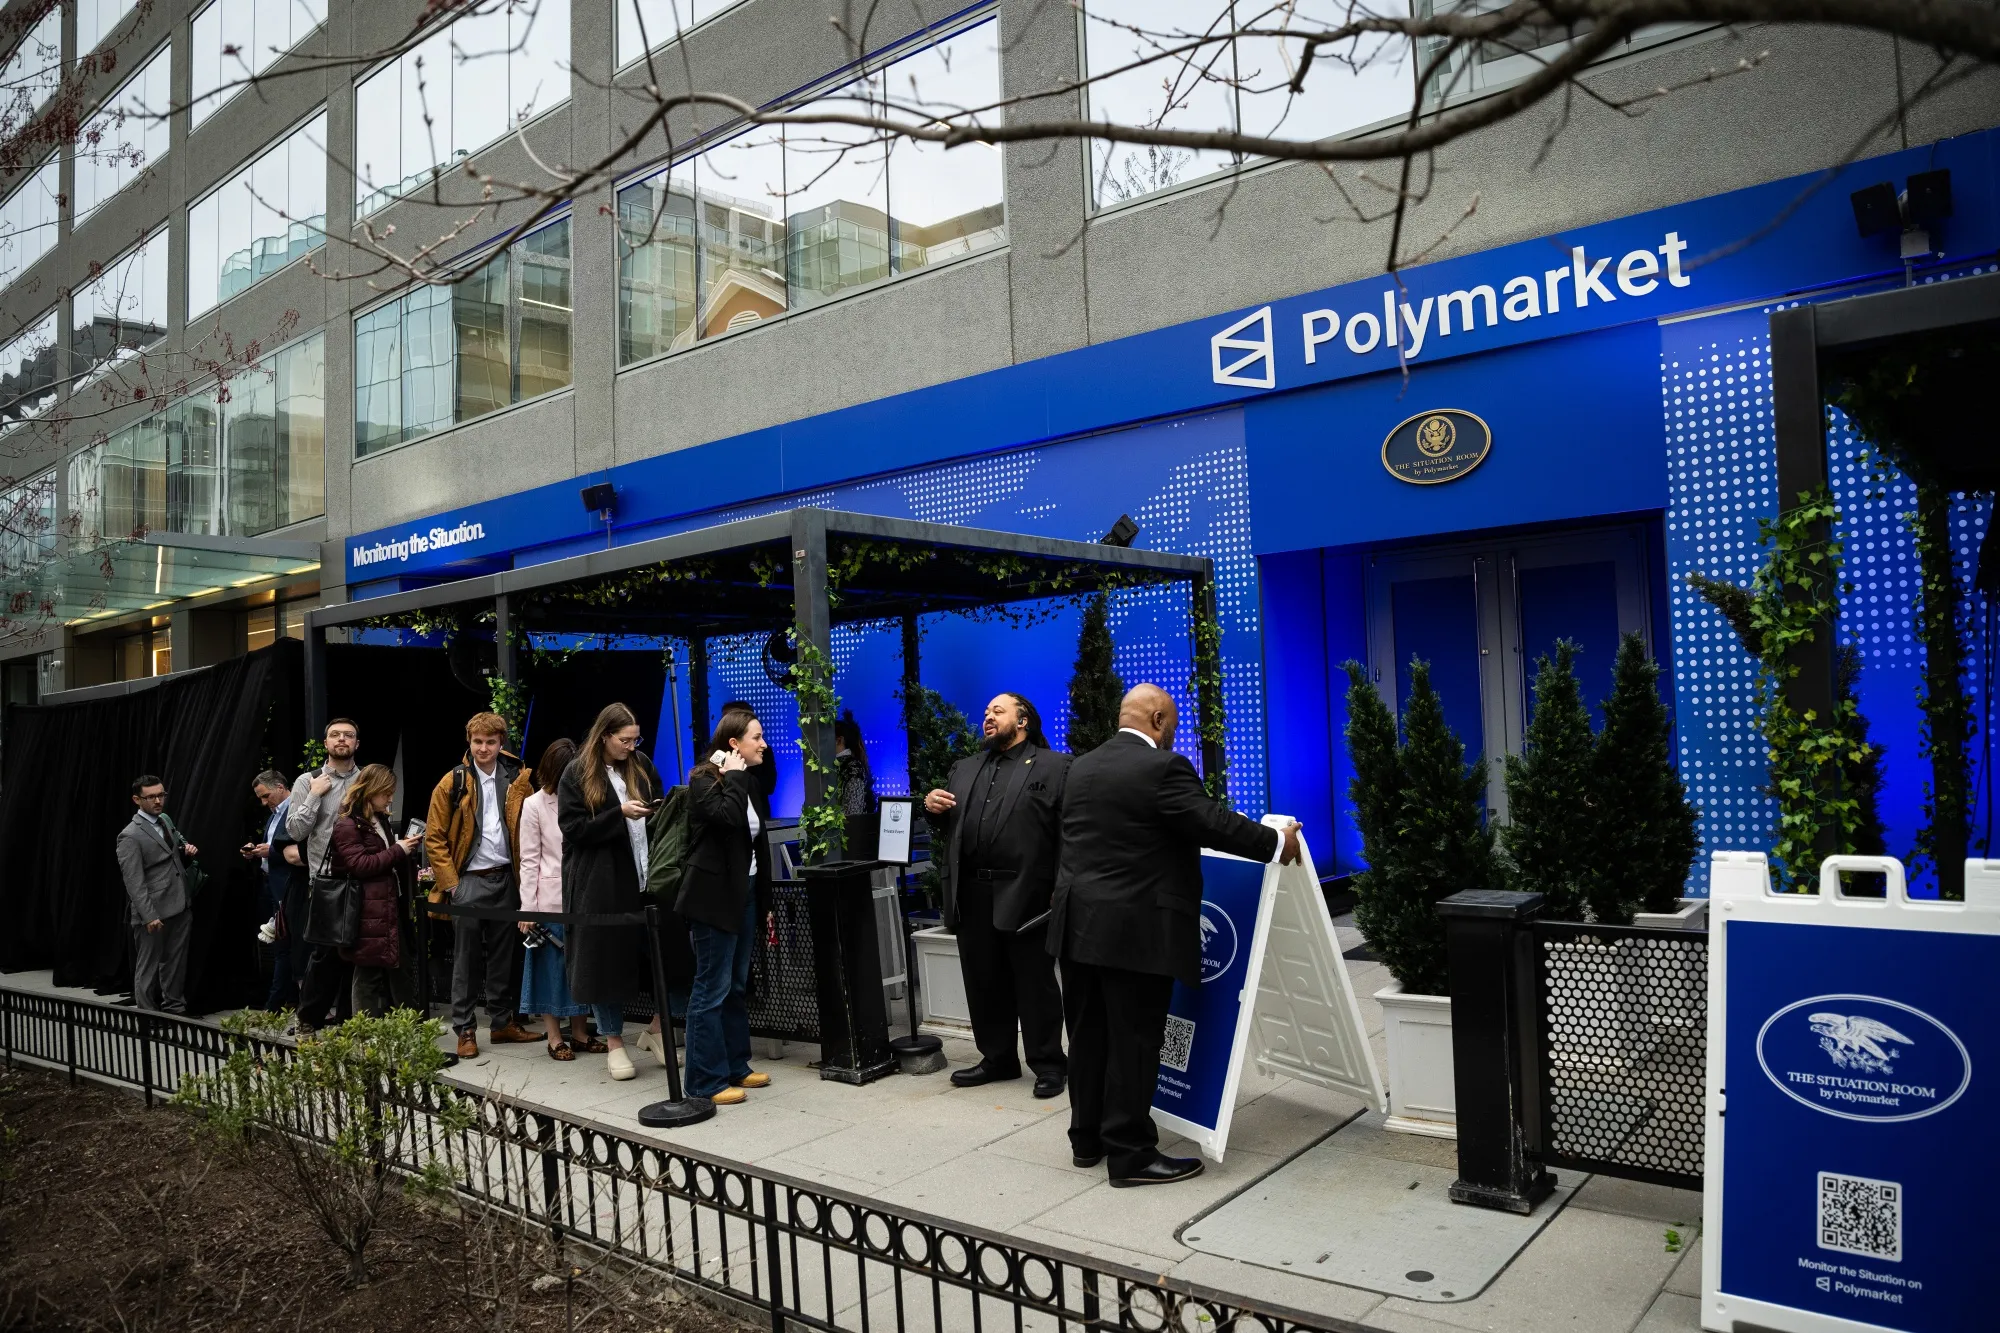
On Polymarket, the U.S.-based prediction-market platform, traders can wager on the outcome of the city’s mayoral election. Similar markets have appeared for Toronto, Windsor and even Stratford. What once looked like an obscure experiment in forecasting has moved remarkably quickly toward the mainstream.
Over the past two years, commercial prediction markets have grown from niche instruments used by political obsessives and forecasting enthusiasts into increasingly sophisticated financial platforms. Users buy and sell contracts whose value depends on whether an event occurs: Who wins an election? Will the Federal Reserve cut interest rates? Will a particular economic target be reached?
Prediction Markets Have Exploded in Scale
Combined monthly global trading volume on Kalshi and Polymarket, July 2024–July 2026
65× — approximate increase in monthly trading volume in just two years.
Source: Pew Research Center analysis of The Block data, September 2026. Polymarket figures include Polymarket US.
The attraction is obvious. Markets aggregate information quickly. Unlike an opinion poll, which offers a snapshot of what respondents say at a particular moment, a prediction market produces a continuously changing probability. New information arrives, traders react and the price moves.
But something important changes when prediction markets become mass-market products.
The question is no longer simply whether markets can predict events accurately. It is whether societies are prepared for a financial product that combines politics, speculation and the mechanics of online gambling—and can place all three in the palm of a voter’s hand.
A 2024 U.S. federal court ruling that opened the door for regulated political-event contracts accelerated the expansion of platforms such as Kalshi and helped legitimize an industry that had previously occupied a regulatory gray zone. Polymarket has also become increasingly prominent in political conversation.
The result is an unusual experiment. Elections are becoming simultaneously civic events, information products and tradable assets.
That deserves more scrutiny than it is receiving.
Gambling by Another Name
Prediction markets prefer the vocabulary of finance. Participants “trade” contracts. Markets have “prices.” Those prices supposedly encode probabilities.
Economically, that language makes sense. Psychologically, however, the distinction between trading and gambling can become much less clear.
A user puts money at risk on an uncertain future event and receives more money if the prediction proves correct. Digital platforms can provide immediate feedback, constant opportunities to place new positions and an effectively endless stream of events on which to speculate.
Those characteristics should sound familiar.
They resemble many of the features that have made online sports betting so commercially successful—and potentially harmful.
The experience of sports gambling should make policymakers cautious. After the U.S. Supreme Court cleared the way in 2018 for states to legalize sports betting, mobile wagering spread rapidly. Researchers have since documented increases in indicators of gambling-related harm, including searches for help with gambling addiction and calls to gambling helplines. Canada legalized single-event sports betting in 2021, bringing similar questions north of the border.
The Sports-Betting Precedent
What followed the rapid expansion of legal sports betting in the United States
Source: JAMA Internal Medicine, 2025. Wager and sportsbook figures as reported in the study.
The concern isn’t that everyone who buys a prediction-market contract will develop a gambling problem. Most won’t. The concern is that digital markets dramatically reduce the friction that once limited gambling.
There is no casino to enter and no betting counter to visit. A wager can be made from a phone while sitting at home, riding a train or watching an election debate.
That matters because gambling harms aren’t distributed evenly. Research has repeatedly found that young people and individuals vulnerable to addictive behavior face greater risks. Public-health research has also associated gambling problems with depression, anxiety, substance abuse, financial distress and self-harm.
Gambling-Addiction Help Searches Rose After Sportsbooks Opened
Estimated increase above expected search levels in eight U.S. states
Source: JAMA Internal Medicine, 2025. Percentages represent estimated increases in Google searches seeking help for gambling addiction after sportsbooks became operational.
Prediction markets didn’t create these problems. But their design can reproduce some of the mechanisms behind them.
And political markets introduce another complication that sports betting doesn’t.
The thing being wagered on is democracy itself.
When Odds Become Political Information
Voters traditionally encounter elections through news reports, campaign advertising, debates, rallies, conversations and opinion polls. Prediction markets add something new to that information ecosystem: a constantly updating numerical judgment about who is likely to win.
A candidate isn’t merely leading or trailing. The market says she has a 72% chance of victory.
That number carries psychological authority. It looks precise. It moves in real time. And because money is supposedly behind it, users may assume it reflects information superior to conventional polling.
Sometimes it might.
Prediction markets have a respectable forecasting record, and their defenders make a powerful argument: People who have money at stake have incentives to incorporate information rather than merely express preferences. Markets can synthesize dispersed knowledge faster than traditional institutions.
But much of the research establishing prediction markets’ forecasting value comes from an earlier era, when such markets were smaller and often populated by highly engaged participants following particular elections closely.
Mass adoption changes the experiment.
Today’s prediction markets can attract enormous attention and participants who aren’t political specialists. Their prices can also move when large traders take substantial positions. Traders may possess unequal information, and the public often has less visibility into who is moving a prediction market than it has into the methodology of a reputable opinion poll.
A poll can be interrogated. Who was surveyed? How large was the sample? What was the margin of error? How were respondents selected?
A market price looks simpler: 63%.
Its apparent simplicity may obscure how that number was produced.
This creates a potentially important feedback loop. Traders respond to political events. Journalists and voters observe the resulting odds. Those odds become news. That news can affect perceptions of candidates, fundraising, enthusiasm and perhaps even voting behavior.
The market isn’t merely forecasting the political conversation anymore. It may become part of the political conversation it is attempting to forecast.
We don’t yet know how consequential that effect will be. That uncertainty is precisely why governments should pay attention now rather than after prediction markets become embedded in election coverage.
Canada Can’t Simply Ignore Them
Canada presents an instructive case.
Companies currently can’t simply establish domestic political betting markets for Canadians. Yet national borders mean increasingly little to an information ecosystem built around globally accessible digital platforms.
A Canadian voter doesn’t have to place a wager to encounter prediction-market odds. They can appear in news stories, social-media posts, television commentary and political discussions.
That means the relevant policy question is larger than whether Canadians should legally be permitted to bet on elections.
It is also whether political prediction markets should be treated as gambling, financial products, information platforms—or some combination of all three.
Each classification produces different regulatory instincts.
If they are primarily markets, regulators may emphasize transparency and market integrity. If they are gambling products, policymakers may focus on addiction, age restrictions, advertising and wagering limits. If they increasingly influence political information, election regulators and democratic institutions may have legitimate interests as well.
The mistake would be choosing one category too quickly.
Regulate Before Normalizing
None of this necessarily justifies banning prediction markets. They may provide useful information, and governments should be wary of suppressing innovative financial instruments simply because they are unfamiliar.
But “innovation” isn’t an exemption from regulation.
There are intermediate options: wagering limits, age and identity verification, restrictions on advertising, greater disclosure of large positions, transparency requirements and specific safeguards for political markets.
The first step, however, is more basic.
We need to understand how people actually use these platforms.
Do users regard political contracts as investments, forecasts, entertainment or gambling? Does seeing market odds alter perceptions of candidates? Are younger users disproportionately attracted to these products? Do political markets create the same patterns of compulsive participation seen in other forms of digital wagering? How much public support exists for allowing people to wager on elections in the first place?
These aren’t merely academic questions. Prediction-market companies have powerful incentives to expand into new jurisdictions and new categories of events. If political markets follow the trajectory of sports betting, regulators may soon find themselves responding to an industry that has already achieved mass adoption.
Societies have repeatedly struggled with this sequence in the digital age. A technology scales first. Its social consequences emerge second. Regulation arrives third.
Artificial intelligence, social media, cryptocurrency and online gambling have all demonstrated the difficulty of governing technologies after their habits and business models become entrenched.
Prediction markets offer an opportunity to reverse that order.
Their advocates may be right that markets can produce valuable forecasts. Their critics may also be right that wrapping gambling mechanics in the language and interface of financial trading creates new public-health risks.
Both things can be true.
What shouldn’t happen is for the debate to begin only after betting on elections has become an ordinary part of political life.
Prediction markets are arriving in politics before we know what citizens think of them—or what they will do to citizens.
The odds may start speaking before the public does.