Every major central bank now insists it is building a digital currency. Almost none of them are winning the argument that actually decides these projects: why should anyone use it?
Look at the last five years of retail central bank digital currency (CBDC) launches and a pattern emerges that policymakers still treat as a design footnote rather than the core problem. These projects have been engineered as if sovereignty, security, and adoption are three independent boxes to check — build something the state controls, make it compliant with anti-money-laundering and sanctions regimes, and users will follow. They haven’t. Retail payments are a two-sided market: merchants accept an instrument because consumers already hold it, and consumers hold it because merchants already accept it. An instrument that clears every compliance and sovereignty requirement but never crosses that threshold doesn’t fail quietly — it stalls, gets repurposed, or gets quietly rebuilt.
Three cases make this concrete: China, which has had to dismantle and rebuild its flagship CBDC around the commercial banks it was meant to bypass; the eurozone, which is trying to design around the same failure before it happens; and India, which has already solved the underlying problem — just not with the CBDC everyone assumed would solve it.
China: The Restructuring Nobody Wanted to Announce
The People’s Bank of China’s eCNY is the largest retail CBDC pilot on earth, with roughly 260 million wallets opened since 2019. By any adoption measure, it was also stuck. Alipay and WeChat Pay controlled over 90 percent of China’s mobile payment volume by late 2025, and years of state backing never meaningfully dented that share. The issue was never technical. Chinese consumers already had two fast, free, near-universal apps well before the eCNY existed, and the central bank’s version gave them no reason to switch.
In January 2026, Beijing responded by restructuring the system instead of continuing to push it uphill. Retail eCNY balances were rerouted onto commercial bank balance sheets, with the People’s Bank stepping back to run the underlying settlement layer while banks manage the consumer-facing accounts. That is, in effect, an admission that a central-bank-branded wallet competing head-on with entrenched private platforms could not win adoption on its own terms — even with the regulatory power to mandate participation and the resources to subsidize it indefinitely. Whether this converges toward something resembling a regulated stablecoin model or becomes a distinct Chinese hybrid is still unresolved. What’s not in question is the sequence: build the sovereign, secure instrument first, discover it has no user-side edge, and only then start redesigning around the piece that was missing all along.
The Eurozone: Trying to Design Around the Trap in Real Time
The European Central Bank is the most interesting live test of whether a central bank can see this failure coming and route around it — though its early architecture suggests old instincts are hard to shake.
The digital euro has moved from years of investigation into active piloting. In July 2026, the ECB selected 36 payment service providers — a mix of major banks like Deutsche Bank and UniCredit alongside non-bank platforms like Revolut, Adyen, and Stripe — from more than 50 applicants, ahead of a pilot beginning in the second half of 2027 and a possible first issuance in 2029. Just this month, the Eurosystem opened a call for e-commerce and mobile merchants to join that same pilot, testing a “beta digital euro” in live checkout environments.
The design choices being built in now are the tell. The digital euro will carry a holding limit to prevent large-scale deposit flight from commercial banks, no interest on balances, offline functionality, and free basic services for consumers, with capped merchant fees and no scheme fees for issuing or acquiring banks. This is a genuine attempt to bake in the lesson that adoption requires a real price and convenience edge — rather than discovering that need five years into a stalled pilot, the way China did.
But the constraint facing every advanced-economy central bank is still fully present. The ECB cannot risk destabilizing the commercial banking system it depends on to transmit monetary policy — which is exactly why the holding limits and no-interest rules exist, and why the U.S. and EU have separately restricted yield-bearing stablecoins for fear of pulling deposits out of regulated banks. Card networks and incumbent apps aren’t standing still either. The digital euro’s real test won’t be whether it launches cleanly in 2029; it will be whether Europeans, once it’s live, have any concrete reason to open another payment app when existing networks already clear transactions in under a second. Good architecture is necessary. On its own, it has never been sufficient.
India: The Model, Not the Cautionary Tale
India is the case that resolves this puzzle outright, and it’s worth being direct about what makes it different: India is the one major economy that has already built a payment system capable of displacing entrenched, expensive incumbents at true national scale — and it did so using exactly the state-coordinated, non-bank-friendly model the rest of the world is still circling.
The Unified Payments Interface, built by the National Payments Corporation of India under Reserve Bank oversight, processed roughly 241.6 billion transactions in 2025, with more than 550 million users — a scale no CBDC anywhere has come remotely close to touching. The reasons are instructive rather than accidental: India set a zero merchant discount rate as a matter of policy, financed by a Cabinet-approved subsidy, so cost savings actually reached users instead of being absorbed upstream. And critically, the Reserve Bank kept sovereign control over data and settlement while opening the consumer-facing layer to competition — letting PhonePe, Google Pay, and Paytm build interfaces directly on top of a state-owned rail. The result disproves the assumption that sovereignty and open markets are in tension: India proved a central bank can hold the settlement layer and still let a thick, innovative private market build on top of it, generating the kind of network effects no single-issuer wallet can produce alone.
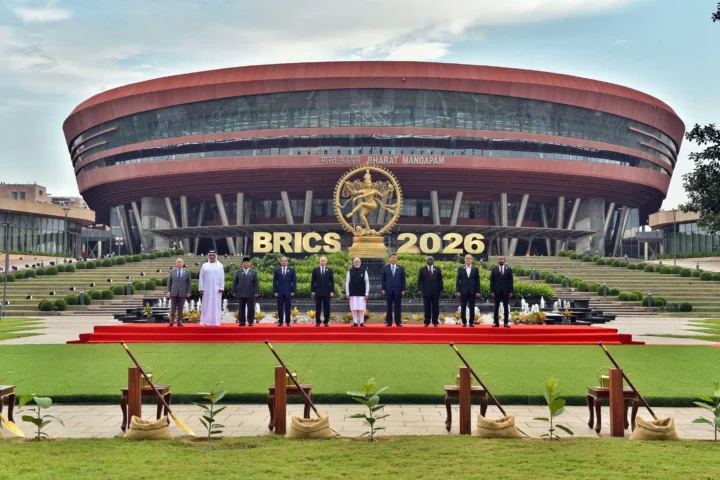
That same instinct — build the rail, then let the ecosystem do the rest — is now visible in how the Reserve Bank is deploying its digital rupee. Rather than trying to force a standalone wallet to compete with a payments system its own citizens already use hundreds of billions of times a year, the RBI has redirected the e-Rupee toward the jobs a programmable, sovereign digital instrument is actually best suited for. It has folded the digital rupee into direct-benefit-transfer welfare programs in states including Gujarat, Puducherry, and Chandigarh, using its programmability to ensure food-subsidy payments are redeemable only at fair-price shops and identified merchants — a use case that plays directly to a CBDC’s core strength: verifiable, trackable, fraud-resistant public disbursement, rather than trying to out-convenience a payments app people already love. At the same time, the RBI is extending the instrument outward: pursuing cross-border CBDC arrangements with Singapore and the UAE, participating in Bank for International Settlements multilateral pilots, and proposing to link CBDCs across BRICS members at the 2026 summit India is hosting.
Put together, that’s not a country failing to replicate a retail win — it’s a country running two complementary systems in parallel and using each for what it does best: UPI for the daily, high-volume, consumer-facing payments race it has already won outright, and the digital rupee for the sovereign, cross-border, and public-disbursement functions that a bank-app ecosystem was never going to solve on its own. It’s the most coherent digital-currency strategy any major economy has produced so far, precisely because it doesn’t force one instrument to do a job it was never suited for.
The Uncomfortable Part for Everyone Else
The lesson that follows is more radical than most central banks are prepared to act on: don’t authorize a sovereign retail rail until it can demonstrate an actual cost-and-speed advantage over whatever people already use, and stop pouring resources into permissioned, bank-only CBDC pilots when open, UPI-style fast-payment rails — state-owned settlement, non-bank interfaces, sub-incumbent pricing — have already been proven at scale.
That’s a harder sell in Washington, Frankfurt, and Tokyo than it was in New Delhi, for a structural reason worth stating plainly: advanced-economy central banks can’t risk destabilizing the commercial banks they depend on for monetary policy transmission the way India could when it built UPI around competition rather than protection. That’s exactly why the digital euro is being built with holding limits and no interest, and why FedNow — itself a fast-payment rail, not a CBDC — reached $853 billion in transaction value in 2025 but still trails the privately run Clearing House RTP network’s $1.3 trillion, in a market where it offers no clear price advantage over what already exists.
There’s a real cost to getting this wrong beyond wasted pilot budgets, too. When sovereign digital instruments underdeliver on utility, the gap doesn’t stay empty — shadow infrastructure fills it, from ruble-pegged settlement networks to stablecoin remittance corridors that win specifically because they route around Western compliance regimes. Every year a G7 central bank spends perfecting a compliant, sovereign, but unused wallet is a year that gap gets wider.
The takeaway from China, the eurozone, and India isn’t that CBDCs are a bad idea. It’s that sovereignty and security were never the finish line — they were the entry fee. The race is won on the two-sided market problem: give people and merchants something cheaper and faster than what they already have, on a rail open enough for competitors to build on it, and adoption follows on its own. India figured that out. The question is how many other central banks are willing to admit it before they, too, have to quietly rebuild what they’ve already launched.